
ECB vulnerability standards from January 2027: what should enforcement firms check in their letters?
Enforcement Conduct Board (ECB) vulnerability standards start in January 2027. Seven practical checks for enforcement letters, contact routes and records.
The customer is holding the letter. Can your agent see it?
When a customer calls about a letter, can your agent see the same document? A practical check of contact-centre access, guidance and communication records.
Forbearance letter wording: can the customer understand the support offered?
Review forbearance letters against the support offered. Check payment terms, balance and credit-file explanations, and keep creditor and agency wording aligned.
FCA information request deadlines: how to assemble the letter evidence pack
Responding to an FCA information request? Check which deadline applies and assemble a letter evidence pack linking approvals, generation, output and sending.
BNPL missed-payment notice: what CONC 7.20 requires
What FCA rule CONC 7.20.1R requires a missed-payment notice on regulated deferred payment credit to tell the customer, and how to check yours.
BNPL collections handover: what notice evidence should travel with the account?
What notice evidence should travel with a BNPL account? A practical checklist covering approved versions, generation records, retained outputs and sending results.
When a Customer Demands a Deed of Assignment: Is Your Approved Response Ready?
CSA guidance on Deed of Assignment myths, genuine subject access requests and keeping collections responses appropriate, approved and traceable.
Consumer Duty communications evidence: what should your record show when a complaint arrives?
What the Consumer Duty and DISP expect when a complaint questions an arrears letter, what the FCA found in March 2026, and what your record should show.
CONC 7 arrears communications: what rules apply, and which approved version was generated?
What the CCA and CONC 7 require in arrears communications, and how collections teams can show which approved version generated each letter.

When AI Sounds Regulated: The FCA’s Warning on Investor Trust
FCA research reveals misconceptions about AI financial information. What should firms check when AI helps shape customer communications?

When Systems Fail, Who Approves the Customer Update?
The FCA’s resilience exercise raises a practical question: can your team prepare, approve and track customer updates when disruption affects several firms?

£4.7 Million: When Regulatory Change Outruns Operational Controls
Explore Citibank’s £4.7m sanctions penalty, OFSI’s findings and the practical lessons for regulatory change, operational controls and communication governance.

When One Mobile Mast Fails: What Ofcom’s Proposed Incident-Reporting Changes Could Mean
Ofcom is proposing new mobile and rural telecoms incident-reporting thresholds. See what providers should understand and prepare for.
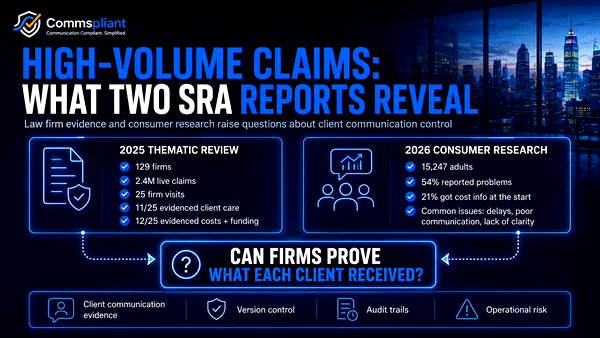
High-Volume Consumer Claims: What Two SRA Reports Reveal About Client Communication Evidence
A practical overview of two SRA reports on high-volume consumer claims, what they found about law firm practices and consumer experiences, and why firms need reliable evidence of what each client received.

When Council Letters Become Harder Than They Need to Be
Small councils often manage recurring letters across spreadsheets, CSV files and manual processes. See how CommsPliant can simplify control, approval and evidence.

Senior FCA Official Urges Financial Firms to Use ECCTA Information-Sharing Powers
A senior FCA official is urging financial firms to use ECCTA information-sharing powers as government guidance highlights audit trails and decision records.

Off-the-Shelf Controls Aren't Enough: The Operational Lesson Behind the FCA's Annex 1 Warning
The FCA is increasing scrutiny of Annex 1 firms. We look at the operational lesson for regulated communications, governance and audit-ready evidence.
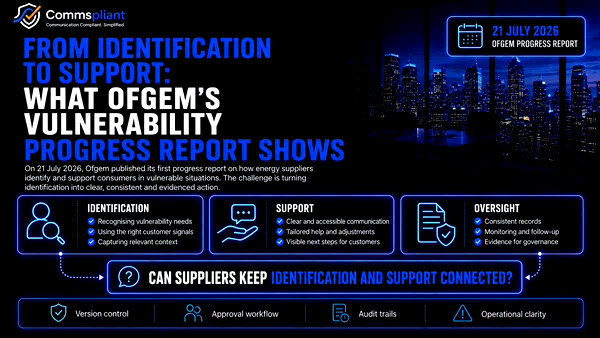
From Identification to Support: What Ofgem’s Vulnerability Progress Report Shows
Ofgem’s July 2026 progress report examines whether identifying customer vulnerability leads to clearer communication, timely support and better outcomes.
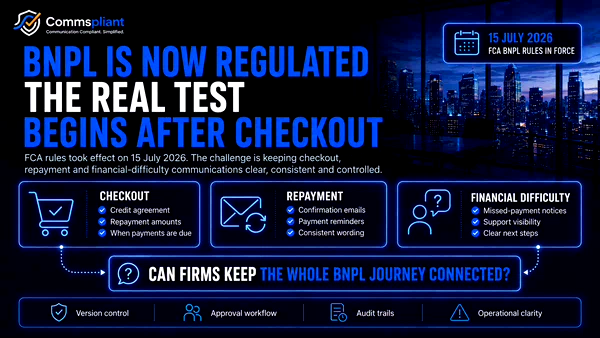
BNPL Is Now Regulated. The Real Test Begins After Checkout
BNPL regulation now reaches far beyond checkout. This practical overview explains the new UK rules, what changed, and why clear, connected customer communications matter throughout repayment and financial difficulty.
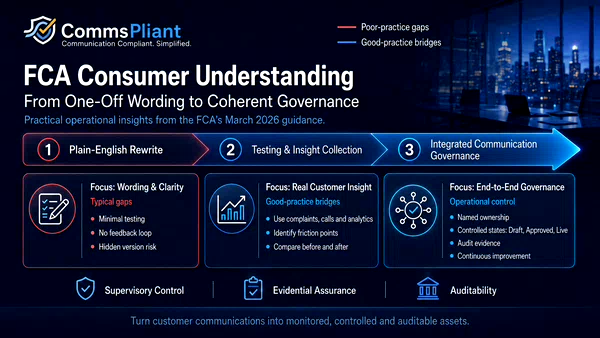
FCA Consumer Understanding: A Human Summary for Regulated Firms
A plain-English summary of the FCA’s March 2026 consumer understanding publication, with practical takeaways for regulated firms reviewing customer communications, testing, monitoring and governance.